FloatMe: Fast Cash Advance App

Screenshots
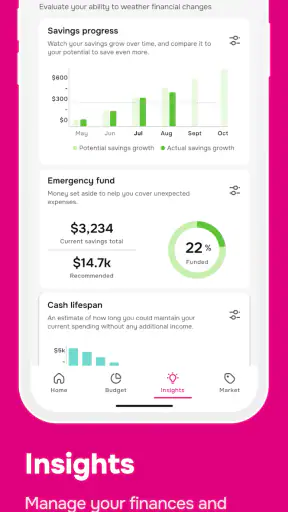
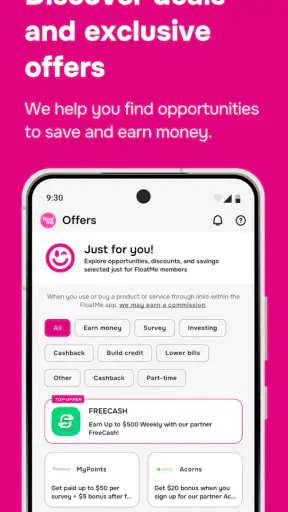
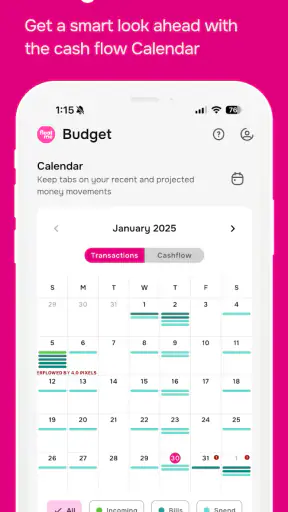
Details
- Rating
- 20.17K reviews
- Version
- 8.21.0
- Developer
- FloatMe
Analysis by Norviv
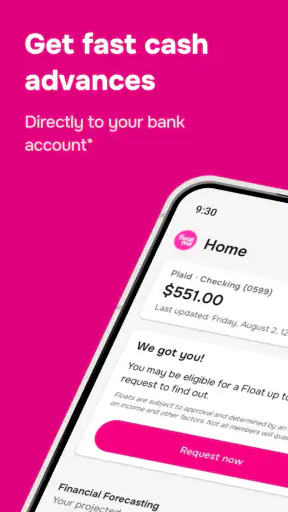
When I opened FloatMe: Fast Cash Advance App, I understood its appeal quickly: it is built for the uncomfortable gap between an expense arriving and payday catching up. This is a finance app from FloatMe that focuses on cash advances, with the store summary presenting them as having no interest or credit checks. That makes it sound simple, but using any advance service well requires more discipline than tapping a button when the balance looks low.
My overall impression is that FloatMe is most useful as a short-term buffer, not as a replacement for regular income or a long-term borrowing plan. The app is free to download, rated for Everyone, and available for devices running Android 7.0 or later. Its current version is 8.21.0, so compatibility should be comfortable for people using older Android phones as well as newer models.
The app has also attracted a substantial audience: it has passed one million installs, with an average rating of 4.5 from roughly seventy-seven thousand ratings and about twenty thousand written reviews. Those figures suggest that the basic idea works for many people, although popularity should not replace checking the terms shown to you personally before accepting an advance.
How I Would Use FloatMe From the First Check to Repayment
I’d use FloatMe as a deliberate bridge, not a last-second assumption: first identify the bill, then check the account and request details, and finally make sure repayment fits the next pay cycle. If setup or a request stalls, I’d pause before repeating steps and verify the basics before deciding whether the app or the underlying account needs attention.
Start by Treating It as a Timing Tool
The most sensible baseline workflow begins before an emergency appears. I would install FloatMe, review the account setup carefully, and look at what the app makes available before assuming that money will arrive immediately. A cash advance app is only helpful when the request, delivery, and repayment timing fit the actual problem.
For example, imagine that a utility bill is due two days before payday and the checking account is short by a modest amount. FloatMe may be useful in that narrow situation because the need is tied to timing rather than a permanent monthly deficit. I would first confirm the amount required, check the repayment date, and make sure the next paycheck can cover both the advance and ordinary bills. That last step matters more than the speed of the request.
I would not use the app simply because the available amount appears tempting. The practical question is not “How much can I get?” but “What will my account look like after repayment?” If taking an advance causes another shortage immediately afterward, the app has only moved the problem a few days forward.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Read the Request Screen Like a Budgeting Document
People often rush through financial app screens because they are already stressed. My advice is to slow down at the point where the advance amount, delivery details, repayment information, and any applicable membership or service conditions are shown. The store description highlights no interest and no credit checks, but that does not mean every part of the service should be treated as cost-free or consequence-free.
Before confirming, I would look for the exact amount that will be received, the amount expected back, and the date or process connected with repayment. I would also check whether the request is going to solve the original expense or merely make the account balance look healthier for a short time. This habit is more valuable than repeatedly checking the app for a larger available advance.
A useful personal rule is to write the repayment amount in the same place where I track rent, subscriptions, and other fixed commitments. That prevents the advance from disappearing mentally after the immediate bill has been handled. FloatMe can make access feel easy; my budget needs to make repayment visible.
Use It for a Specific Gap, Not General Spending
The strongest use cases are concrete: an essential purchase, a necessary bill, or a brief mismatch between income and an unavoidable payment. I would be much more cautious about using it for restaurant spending, impulse purchases, entertainment, or shopping that can wait until payday. Those uses turn a timing tool into a habit of spending future income early.
This distinction also helps answer whether FloatMe is right for you. Someone with predictable pay and an occasional short gap may find it practical. Someone whose expenses regularly exceed income needs a broader solution, such as a revised budget, a conversation with bill providers, or a longer-term financial counseling option. No fast advance app can repair a recurring monthly shortfall by itself.
Keep the Repayment Day Visible
After using an advance, I would add a reminder to my calendar and leave enough room in the bank account for the expected repayment. I would not rely only on memory or on seeing a notification. A simple reminder placed several days before payday can prompt me to pause optional spending and avoid creating a second shortage.
This is one of the less obvious differences between careful and careless use. The advance request takes a minute, but the repayment affects the rest of the pay cycle. Experienced users treat the repayment date as part of the original transaction, not as a separate problem to handle later.
Settings and Account Details Worth Checking
Once the basic workflow is clear, I would spend a few minutes reviewing the app’s account and notification settings. The exact screens can change between releases, but the principle is stable: make sure the contact information, connected account details, and notification preferences are current. An outdated detail can create unnecessary friction precisely when the user needs a fast answer.
Notifications deserve special attention. I prefer alerts that help me track request status, upcoming repayment information, and account activity, while avoiding a flood of messages that makes important notices easy to ignore. If FloatMe offers separate controls for different kinds of alerts on the device, I would keep financial activity enabled and reduce anything that feels distracting.
I would also check the app after an update rather than assuming every preference remains exactly where I left it. The current version is 8.21.0, and updates can change navigation even when the main purpose stays the same. A quick review of the home screen and account area is worthwhile before an urgent request.
Security settings should be handled with the same care as the money itself. I would use a strong device lock, avoid signing in on a shared phone, and verify that I am interacting with the official FloatMe application from FloatMe rather than an imitation. A finance app should never be treated like a casual game simply because its interface is straightforward.
Do Not Confuse a Smooth Interface With Guaranteed Access
One point I would make clear to a friend is that an easy application flow does not guarantee that every request will be approved, delivered in the same way, or available for the amount expected. Eligibility and availability can depend on the account and the circumstances shown inside the app. I would therefore avoid planning a bill around money that has not actually arrived.
This is especially important for deadlines. If a payment is due today, I would not wait until the last possible moment to request help through FloatMe. I would first explore whether the biller offers a grace period, scheduled payment, or another arrangement. The app may be useful, but it should not be the only plan for an urgent obligation.
Build a Repeatable “Before I Tap” Routine
My repeatable routine would take less than a minute. I would identify the exact expense, compare it with the amount needed, check the repayment impact, and confirm that the account information is current. Then I would decide whether an advance is genuinely cheaper and safer than the alternatives available to me.
That last comparison is important. If delaying a nonessential purchase costs nothing, waiting is better. If a biller allows a free date change, that may be preferable. If a trusted person can help without creating a complicated obligation, that may also be worth considering. FloatMe is convenient, but convenience is not automatically the best financial choice.
Shortcuts That Actually Make the Experience Better
The most useful shortcut is not a hidden button; it is preparing before the emergency. I would keep the app updated, maintain accurate account details, and know where to find the request and repayment information. That reduces the chance of making a rushed decision while trying to remember how the app works.
I would also keep a small note in my budgeting app or notebook showing any active advance and its repayment date. This prevents a common mistake: checking the bank balance, seeing the incoming money, and forgetting that part of it is already committed. FloatMe handles the advance workflow, but a separate personal record gives me a clearer view of the whole pay cycle.
Another useful pattern is to review the reason for each request afterward. If the same type of expense appears repeatedly, I would treat that as a budgeting signal. Repeated transport costs, medication expenses, or bill timing problems may point toward a monthly adjustment that will help more than another advance. The app can reveal a pattern even if it cannot solve the underlying cause.
Where the App Can Save Time
FloatMe is convenient when the need is small, specific, and close to payday. The no-interest positioning makes it distinct from many traditional credit products, and the lack of a credit check may make it more approachable for people who do not want a conventional credit inquiry. For a user who already understands the repayment plan, that can be a meaningful advantage.
It can also be less burdensome than applying for a credit card or personal loan when the amount needed is modest and the problem is temporary. Traditional products may involve longer applications, credit decisions, or a borrowing structure that is excessive for a single short gap. FloatMe’s focused design is better suited to that narrow situation.
Still, “faster” does not mean “always available at the exact moment.” I would use the app as one part of an emergency plan, never as proof that an urgent expense is covered until the funds and repayment details are clear inside the account.
Advanced Limits: The App Is Not a Monthly Income Extension
The biggest limit is behavioral. Even an advance with no interest can become expensive in practical terms if it causes missed bills, overdrafts, late payments, or repeated dependence on future earnings. The absence of a traditional credit check does not remove the need to evaluate affordability.
I would set a personal ceiling below whatever maximum the app displays. My limit would be based on the amount I can repay comfortably while still covering essentials, not on the largest amount offered. This is an advanced but simple safeguard: the provider’s available amount is not the same as my safe amount.
I would also avoid stacking decisions. If one advance is already active, I would not immediately look for another way to cover unrelated spending. The more commitments overlap, the harder it becomes to see the real balance of the next paycheck. A clean account history is more useful than repeatedly stretching the available buffer.
When Another Option Is Better
FloatMe is not my first recommendation for someone dealing with ongoing debt, unstable income, or bills that are larger than a short-term advance can reasonably cover. In those cases, a conversation with creditors, a structured repayment plan, a local assistance program, or professional financial guidance may be more appropriate.
I would also compare it with an existing bank overdraft arrangement, an employer-provided earned-wage option, or a no-fee payment extension. The best alternative depends on the actual terms and the user’s situation. A conventional savings buffer is usually healthier when it is available, because it avoids turning the next paycheck into a repayment event.
People who dislike linking financial accounts, monitoring repayment dates, or reading service conditions may find the app stressful rather than helpful. The interface may be accessible, but responsible use still requires attention. Anyone looking for a rewards program, investment tools, credit building, or full budgeting software should choose a product designed for those purposes instead.
Who I Think Will Get the Most From It
I see FloatMe as a good fit for an adult who occasionally needs help bridging a short, predictable gap and is willing to track repayment carefully. Its Everyone content rating makes it broadly accessible from an age-label perspective, but financial maturity matters more than the label. The right user is someone who can distinguish an emergency buffer from extra spending money.
It may also suit someone who wants to avoid a credit check for a small, temporary need. The app’s store summary specifically emphasizes cash advances without interest or credit checks, which explains why it can feel different from credit cards and many loan applications. Even so, I would read the in-app terms every time the circumstances change.
I would steer away from it if the same shortage happens every pay cycle. That pattern suggests the budget needs more income, lower fixed costs, different bill dates, or outside support. Using FloatMe repeatedly in that situation could make the calendar look manageable while leaving the underlying numbers unchanged.
My Mastery Verdict After Looking at the Whole Workflow
After considering the complete experience, I think FloatMe succeeds when it stays in its proper role: a focused short-term cash advance app for a temporary timing problem. It is free, its purpose is easy to understand, and its no-interest, no-credit-check positioning gives it a clear place among finance tools. FloatMe, developed by FloatMe, has also gained enough adoption and user feedback to make it a familiar option rather than an obscure experiment.
My recommendation comes with a firm condition: use it with a written repayment plan. Check the account details, adjust notifications so important activity is visible, request only what the specific expense requires, and treat the next payday as already partly committed. Those habits do more to protect the user than simply knowing where the advance button is.
The app is not a substitute for savings, stable cash flow, or a debt solution. It is also not the best answer when another option can delay the bill for free or when the shortage is recurring. But for a carefully chosen, short-lived gap, I can see why many people rate the experience positively. My final view is favorable but cautious: FloatMe can be useful in an emergency, provided I remain in control of the repayment rather than letting the convenience control my spending.
Frequently Asked Questions
01What is FloatMe: Fast Cash Advance App, and how does it work?
FloatMe is a financial app designed to help eligible users access a small cash advance before their next payday. After creating an account, you typically connect a supported bank account so the app can review income and account activity. If approved, you can request an advance and choose how it is delivered. The available amount, fees, timing, and eligibility requirements may vary by user.
02How much money can I borrow through FloatMe?
The amount available through FloatMe depends on factors such as your connected bank account, recurring income, account history, and repayment behavior. New users may receive a lower limit, while eligible returning users could qualify for more. The app displays the advance amount before you confirm the request, so review the terms carefully rather than assuming a specific limit is guaranteed.
03Does FloatMe charge fees or require a subscription?
FloatMe may use a membership or subscription model, and additional charges can apply depending on the advance option and delivery speed you select. Costs and policies can change, so check the current pricing shown in the app before signing up or requesting money. Make sure you understand any recurring membership charge, expedited-transfer fee, and cancellation requirements.
04How quickly will I receive a FloatMe cash advance?
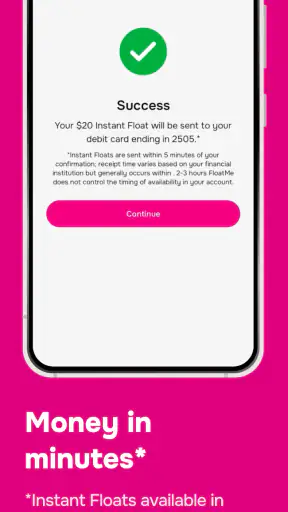
Delivery time depends on the option selected, your bank, account verification, and whether the request is approved during normal processing periods. Standard delivery may take longer, while an expedited option could arrive sooner if available and may involve an extra charge. FloatMe does not guarantee that every advance will arrive immediately, so plan around the stated estimated time.
05What happens if I cannot repay my FloatMe advance on time?
You should review the repayment date and terms before accepting an advance and contact FloatMe support as soon as possible if repayment may be difficult. A missed repayment could affect your ability to use the service again and may create additional account or banking issues, depending on the applicable agreement. FloatMe is not a replacement for long-term budgeting or emergency financial advice.


